My Insurance Coverage Increased... Which Caused My Rate To Increase
Aaron Rosen • August 28, 2023

I received an email from a client last week. He informed me his rate increased on his home insurance by 17%. He also informed me that his coverage increased by 16%. It made me feel really good that he looked at everything and not just the increase in cost.

All things considered that is pretty good. Technically speaking, it was a 1% increase in cost. But as consumers, we are not expecting these big coverage increases, which are ultimately increasing the cost of insurance. I, too, had an increase in both my coverage and cost this year on my homeowners insurance. A 14% increase in coverage and an increase of 8.7% in cost. And that is on top of the 20% rate increase last year and the 20% rate increase the year before (with not that much of an increase in coverage).

At homeowners insurance renewal time, this is the once-per-year adjustment in coverage on your policy. While the cost to rebuild fluctuates throughout the year, the only time the insurance companies can adjust anything is at your renewal time. Some insurance companies have a cap of 6% per year increase in coverage. Others, do not have a cap and some do not change anything. You would have to request an increase in coverage (if you would like). While it sounds like this is the worst thing that could happen, it really is not. The insurance companies want to insure you to 100% of the replacement value of your home (according to their systems). The cost to rebuild has gone up quite a bit in the last few years due to inflation. Depending on where you live, the cost to rebuild used to be $300/sq. ft. at a minimum. Now, it could be as little as $500/sq. ft. (location dependent). GULP! That may sound like a lot, but I would rather have enough insurance than not enough in the event of a loss.

Keep in mind, most insurance companies automatically increase your coverage each year (even if you do not want them to). The replacement cost calculator tool, each insurance company uses, are all a little different. They can calculate different values, and in my opinion, they are not always accurate for most of California (they are usually a little low). It is always a good idea to double check with your insurance agent, if you are unsure about your coverage. The goal is to make sure you are properly insured. 

Elizabeth's Corner
My wife, Elizabeth, is a Mom, an amazing wife and an incredible chef. She trained at the California Culinary Academy in San Francisco. She shares a helpful tip below.

Zucchini season is here and there is nothing better than Zucchini Bread. Here is a great recipe for Chocolate Zucchini Bread. This recipe is courtesy of Two Peas and Their Pod.


Chocolate Zucchini Bread

Equipment:

  • 9 x 5 Loaf Pan
  • Wire Cooling Rack


Ingredients:

  • 1 cup all-purpose flour
  • 1/2 cup Dutch process cocoa or unsweetened cocoa
  • 1 teaspoon baking soda
  • 1/2 teaspoon sea salt
  • 2 large eggs, at room temperature
  • 1/4 cup unsalted butter melted and slightly cooled
  • 1/4 cup canola, vegetable oil, or melted coconut oil
  • 3/4 cup packed light brown sugar
  • 1 teaspoon pure vanilla extract
  • 1 1/2 cups packed shredded zucchini
  • 1 cup semisweet chocolate chips, divided


Directions:

  1. Preheat your oven to 350°F. Grease a 9-by-5-inch loaf pan with nonstick cooking spray and set aside.
  2. In a medium bowl, whisk together the flour, cocoa powder, baking soda, and sea salt. Set aside.
  3. In a large bowl, add the eggs, melted butter, oil, vanilla extract, and brown sugar. Stir until smooth. You might have a few small brown sugar clumps and that is fine.
  4. Stir the dry ingredients into the wet ingredients, don’t overmix. Stir in the shredded zucchini until just combined. Stir in 3/4 cup of the chocolate chips.
  5. Pour batter into prepared pan. Sprinkle the remaining 1/4 cup of chocolate chips over the top of the bread. Bake for 50-60 minutes, or until a toothpick inserted into the center of the bread comes out mostly clean, you might have some melted chocolate chips on the toothpick and that is fine. You just don’t want a lot of gooey batter.
  6. Remove the pan from the oven and set on a wire cooling rack. Let the bread cool in the pan for 15 minutes. Run a knife around the edges of the bread and carefully remove from the pan. Let the bread cool on the wire cooling rack until slightly warm. Cut into slices and serve.
  7. Note-if you use coconut oil, make sure it is melted and slightly cooled. The bread will keep on the counter, wrapped in plastic wrap, for up to 4 days. This bread also freezes well. To freeze, cool the bread completely and wrap in plastic wrap and aluminum foil. Freeze for up to 1 month. Defrost before slicing.

Enjoy!

Aaron Rosen

Arc 23 Insurance

Services

Auto/Home/Life, Umbrella,

Earthquake/Flood, Commercial,

Workers'Comp,

Professional Liability,

Cyber

License # 0L56377

Good Quote:

"Someone is sitting in the shade today because someone planted a tree a long time ago."

- Warren Buffett


Have a Claim?

Call our office

(949) 484-7500

or cell

(949) 441-1244

We will help you.


Companies We Represent

Nationwide

Foremost

Travelers

Bamboo

Guard

CSE

Hippo

Safeco

Stillwater

NatGen Premier

And many more...


Inspirational Quote:

"The best and most beautiful things in the world cannot be seen or even touched--they must be felt with the heart."

- Helen Keller


Trusted Partners

Roofing Company

Mike Duby, Beach Cities Roofing

949-697-6561


Remediation Company

Brian Byers, EHS

949-734-9046


Repiping Your Home

Repipe1

866-737-4731


Health Insurance

Mike Primicerio

949-633-3988


Personal Injury Attorney

Eric Traut

714-835-7000


Estate Planning Attorney

William London

949-474-0940


Auto Body

Rae or Max,

South County Auto Body

949-859-7990

Until next time, if you have questions, concerns, or need some advice, please call our office 949-484-7500. 

Two smiling men standing together in an office hallway, one in a blue blazer and the other in a light blue shirt.
By Aaron Rosen • October 19, 2026
The election is almost here and you probably already have your ballot in hand.
Satellite hurricane map beside a person watering a front yard at a house
By Aaron Rosen • September 22, 2026
A friend of mine called me the other day, who is also a client. He asked me about coverage for water damage, flooding, roof leaks, drainage, etc. What he finally shared with me was his concern about El Niño, this coming winter. If you are not familiar or have never heard of this, it is the cycle the Pacific goes through about every 5 years. In a typical year, trade winds usually push warmer air and water towards Asia. During El Niño, the winds and currents weaken and blow the warmer air back toward the Americas. This stirs up more moisture and more storms in the Pacific, which creates more rain, or snow, depending on where you live. As we chatted about flood coverage and ground water, he determined he did not want a flood policy. He is also now aware that any water that comes into his home, through the ground, would not be covered. As for his roof, if the wind blows off his roof, there should be coverage. If a tree falls on his roof due to a storm, there also should be coverage. I do want to share that we have seen some home insurance policies lose replacement coverage for roofs in recent years. They may now be excluded or reduced to actual cash value. Where we have seen this happen more often is with the CA Fair Plan (but this does not necessarily mean it has happened to you). Since there is no water damage coverage from the Fair Plan, it may be a moot point. However, wind coverage is a part of the CA Fair Plan. ***Please read your policies and look for any roof exclusions or language that says actual cash value. If you do not see those words, you most likely have replacement coverage.*** The question that we began with...is your home ready? Have you looked at your drains and are they clear of debris and roots? Do you have any French drains and are they functioning properly? Do you have any slopes draining towards your home? Do you have any tree limbs hanging over your home that could snap in a storm and cause damage to your roof? Have you had a roof inspection or are you worried about an older roof? Have you walked the perimeter of your home with a different set of eyes? Put on your insurance hat, think about is there anything that will damage my home this winter that I can fix now and prevent it from happening? Since the heatwave is over, winter and El Niño will be here before we know it. Now is the time to get ready.
By Aaron Rosen • August 19, 2026
Over the last several weeks, I have received several phishing emails. If you are not familiar with phishing, it is someone who is trying to gain access to your information through nefarious means, so they can steal your identity, information or even your money. With how quickly artificial intelligence has evolved, it has made phishing a lot easier for these bad actors. The emails I have received are written in a way that they sound like they are purchasing a new home and are in need of a home insurance quote/policy. Once we correspond and ask for a few pertinent details, they provide zero details in their response and they ask us to hop on a zoom call. They may state they have a health condition and prefer to speak over zoom, which is why they do not provide any real information about themselves. This is the phishing attempt; hoping we will click on the link, because we want something they have, so we can engage in selling an insurance policy. If we agreed to hop on a zoom call with them, the link would most likely provide them access to everything on my computer. Fortunately, I was aware of these scams and knew better than to fall for this attempted attack. We never received a link and ceased all communication, blocked and reported the emails as phishing. There are other phishing scams going on as well (too many to share). But one other quick story I will share is a malware scam (I believe). The email may arrive from someone you know, via Paperless POST. It is a friendly envelope with a subject of RSVP to my party or BBQ weekend with Friends and Family (similar to an evite). When you click on any link to view the card or calendar, an email will be sent to everyone in your database, which keeps the virus moving forward. Whether or not it does more damage to you or your information is not completely known (and I hope we never find out). With scams on the rise and digital opportunities at our fingertips, please be vigilant before clicking any links or accepting any requests from people you may or may not know. When in doubt, call the person/business from the saved number you have or by googling them. Do not trust any information in the email as it could be just one digit off and one click away from giving the scam artists everything they want....your information!
Two men in cars beside each other in traffic, one stern and one wide-eyed, reacting through open windows
By Aaron Rosen • July 23, 2026
The other morning, my wife and I were headed home after playing some pickleball. As we were approaching a red light at a major intersection, there was a small street just before it, into a neighborhood. A vehicle happened to turn right in front of us. Elizabeth let out a big gasp as I slammed on the brakes and honked the horn at the driver, who we were about to T-bone. What was interesting to me was....I saw it coming. I noticed a car traveling in the same direction as us, that was about to turn left. That vehicle was blocking the view of the car that turned in front of us. Seeing the car that wanted to turn in front of us, I had a feeling they were going to proceed. My hand was already over the horn in anticipation of a potential need. I laid on the horn as I slammed on my brakes, the driver's eyes lit up, as we were about to hit. Fortunately, we did not hit the car. My brakes worked. Our car stopped before we hit them. While it is hard to anticipate and avoid an accident, we can be prepared. In this instance, I know vehicles turn into the neighborhood, right there. I knew their view was obscured by another car. I was ready. But, there are other moments we are not always prepared. As we roll through summer, we may be on vacation and sometimes forget to pay as close attention to what we are doing. Or, we don't think wildfire season will arrive, because we are on vacation. There are many little (or big) things, we can do, to prepare for fire season. Have you worked on clearing mulch (also known as dried wood chips) from your yard? Have you replaced the vents that bring air into your attic with new vents that will not allow embers to travel into your home? We know wildfires will happen. Will you be able to see it coming and already be prepared?
By Aaron Rosen • May 18, 2026
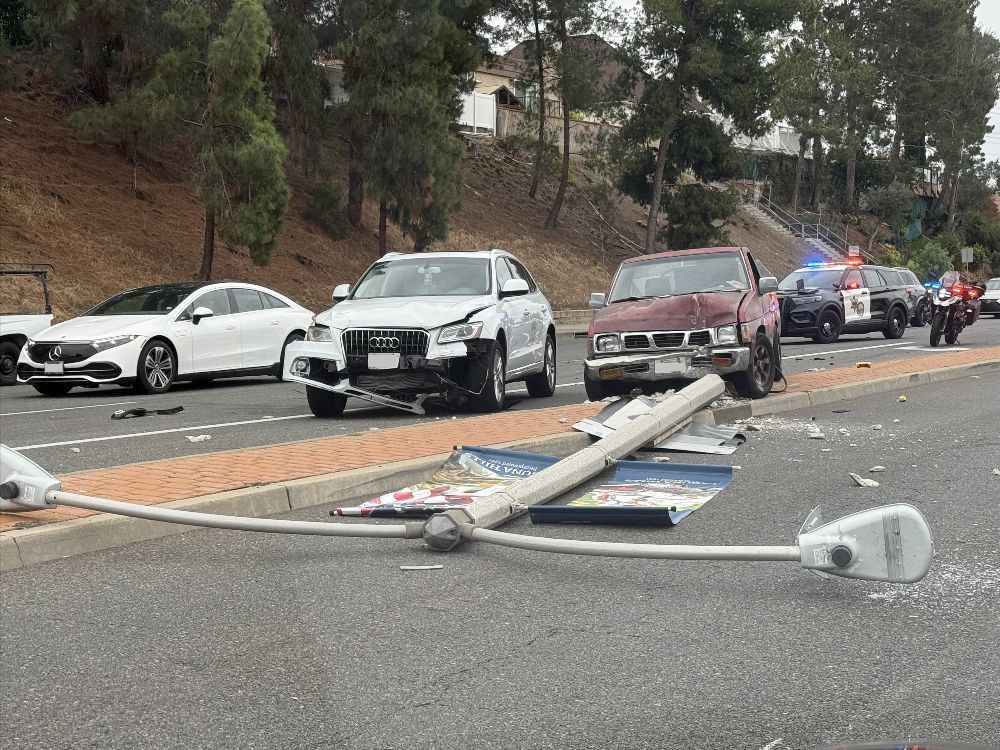
When you see an accident like this, it kind of makes you wonder, who is at fault? I drove past this accident, just last week. At first glance, I could not tell who hit the light pole. And then, I figured it out. What do you think? Who is at fault here? What you cannot see in the picture is that the truck had damage on its rear, leading me to believe the Audi, rear ended it, pushing it into the light pole. If you were the driver of the truck, you may be responsible for paying for the property damage for the light pole, even though the Audi pushed you into it. The good news is, if you are responsible, your insurance company should be able to recoup the money from the Audi's insurance through a process called subrogation. Subrogation is the legal right of an insurance company to seek reimbursement from a responsible third party, after paying a policyholder's claim. We receive a lot of calls from clients about car accidents. First, we want to make sure everyone is ok. Second, we want to know, who caused the accident. If our client did not cause the accident, we have found it best to file a claim against the responsible parties insurance and have them handle all the payments, rental car, etc, directly with you, instead of filing a claim on your own insurance. It helps prevent your insurance company from having to subrogate the claim. It also keeps your record cleaner, with your insurance and helps reduce the possibility of rate increases due to accidents that are not your fault. While insurance companies are not supposed to increase your rates due to not at fault accidents or comprehensive claims, they would also prefer to not pay for them either, as it is their time, people and money to pay those claims. There are times when you may need to involve your insurance company, because the other party is not cooperating. And that is 100% fine. If you can avoid it though, in my opinion, you are better off. For now, drive safe, stay alert, look both ways before proceeding on a green light and as always, if you have any questions, we are here to help.
Child riding a bicycle on one wheel; officials watch nearby outside a building.
By Aaron Rosen • April 30, 2026
Straight from the headlines. You can't make this stuff up. An Orange County mom was charged due to her 14-year-old son hitting a person on his e-bike. If convicted of all charges, she is facing up to 6+ years in prison. Let's provide a little context to what happened. She and her son had already been warned by the police of his reckless riding on a Surron e-bike, that is considered a motorcycle as it can exceed 50 mph, requires a motorcycle license and to be at least 16 years of age. The Surron is considered a Class 3 e-bike, which is illegal (for anyone without a valid license). If this were a Class 2 or Class 1 e-bike (maximum of 20 mph), I believe this may be a different headline. Either way, when your child harms another person, ultimately, you are responsible for their actions. And when you have already been warned that your child is riding an illegal e-bike, and does not behave appropriately on said bike, consequences follow.  So how do you protect yourself, your family and your liability when your child has an e-bike? Here are a few suggestions, in no particular order: Teach your child to ride safely. There is no other good starting point than teaching your child the rules of the road and to ride safely. And hopefully, this started when they were on a non-electrified bike. Many local police departments have started partnering with communities to offer e-bike safety courses for kids. Get an e-bike insurance policy. Call your insurance agent and request a separate policy as e-bikes are typically not covered on your homeowners policy. If you have an umbrella policy, you may want to start with asking if they accept e-bike policies that are offered by another company. Do not allow your child to mod (modify) their e-bike. Some e-bikes can be modified to go faster by unplugging cables or disconnecting lights or connecting to apps to increase speed. Doing so, may change the e-bike from a Class 2 into a Class 3, which are illegal for children to be riding. And last but not least, if you see or hear that your child is participating in risky or illegal e-bike activities, please take steps to hold them accountable for their actions. Maybe it's a mandatory safety course, community service, or removal of the bike all together. As kids, they still have a hard time grasping that their actions can have a massive ripple effect. If they happen to injure someone, advise them to not leave the scene of the crime, as it is considered a "hit and run." There are a few communities that are instituting fines for improper riding or not having the headlight and taillight on at all times. Be aware of the laws and stay current, as I know of several new e-bike laws on the horizon. By now, we have all seen the e-bike gangs. If we can educate each of our children and their friends, hopefully, we can prevent them from getting into an accident and harming themselves, others and being a little bit smarter out on the road.
By Aaron Rosen • March 25, 2026
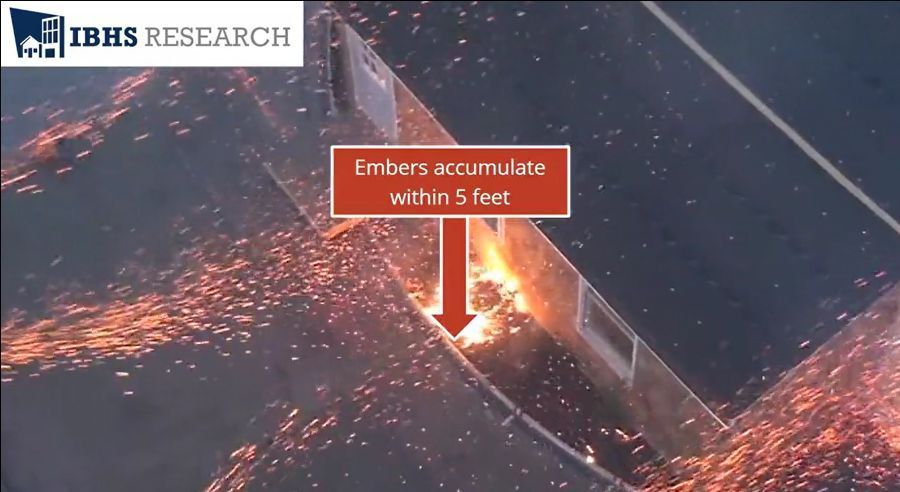
I had the privilege of being invited by an insurance company to a panel discussion on the state of the insurance market in CA. It took place two weeks ago in Los Angeles. The panelists included people from government affairs, lobbyists, and insurance executives. I was one of more than 100 people in attendance. Each panelist was able to speak to their profession. The most common theme I heard from everyone was, prevention is the key to saving your home. One of the panelists was the President of the Insurance Institute for Business & Home Safety (IBHS). The IBHS is "an independent, 501(c)(3) nonprofit scientific research and communications organization supported by property insurers, reinsurers, and affiliated companies. IBHS’s building safety research leads to real-world solutions for home and business owners, helping to create more resilient communities." As the president spoke and showed videos of their research, the videos said it all. The image above is from one of the videos and there is a link to that video if you click on the image. There are quite a few other educational videos here . For the last several years, we have talked about hardening your home, which can mean removing bushes close to your home, enclosing eaves, or replacing the vents to prevent embers from blowing into your attic during a fire. All of this came together, so clearly for me, as I watched these videos . There is logic to not having dried wood, also known as mulch, around your property. Or having a metal gate instead of a wooden gate next to your home. These simple little things, IBHS have proven can save your home, in the event of a wildfire. Please take a moment to watch one or more of the videos. They are truly eye opening and will help you better understand how to make your home safer.
By Aaron Rosen • February 19, 2026
A couple weeks ago, we had a client reach out to ask us, why did my home insurance rate increase so much when I did not file any claims? I think we have all felt this way over the last few years. And when is it going to end? It has been several years of 30-50% rate increases for a lot of us on our home insurance. On car insurance, we have probably seen an increase of 0-20% each year, if you were accident/speeding-ticket free. As odd as it sounds, you can actually track what insurance companies are doing and when they file for a rate change with the state. It is public information and can be found here. If you decide to go down this rabbit hole of data, it is mind numbing, so I've linked the summary pdf for 2025 here . It is a lot easier to digest and see the rate changes in this 18-page doc. Many of the rate filings are program or rule changes. When I look at the data, I tend to look at the overall rate % column. Seeing the rates does not answer the question though: When will it end? I recently had an opportunity to meet a candidate who is running for CA Insurance Commissioner. Her name is Stacy Korsgaden . Before I met her or even read about her, I put together a dozen tough questions I wanted to ask to see if she really knows insurance and understands the market. I felt really good about the questions that she was surely going to fumble over. Then, I googled her. As I started reading, I quickly learned she is a licensed insurance agent (of more than 30 years) and comprehends everything. And once I heard her speak and met her in person, it solidified that she is the right candidate for the job. She is looking deeply at cause and effect of the insurance market in CA. We need more insurance companies to come into the market. Once we have more insurance companies in the market, then the pressure will be reduced on the existing insurance companies capacity issues. More markets, more options over time, should help reduce the cost of insurance. Stacy also pointed out that forests need to be better maintained. We need to manage the ground fuels to help reduce the risk of larger fires. If we do not look at the cause, we will not get the outcome we are looking for. While I do try to stay away from politics, I want to encourage you all to do some reading on the insurance commissioner candidates before the election. Having someone in the office, who has been a licensed agent for so long, has the experience and know-how, who will help steer the ship in the right direction, to help bring in new insurance companies to CA, which in the long run will help stabilize insurance pricing.
Crystal ball with
By Aaron Rosen • January 12, 2026
What Will Happen With Insurance In 2026?
Show More